Voluntary supply meeting compliance demand creates permanent demand signals – and a many-to-many mess of eligibility rules. Four market operators on what comes next.
Voluntary carbon markets are being absorbed into something that behaves much more like a regulated market, and the panel moderated by Dr Daniel Klier, CEO of South Pole, treated that shift as both the opportunity and the problem.
Klier, who came into carbon from financial services, sketched three trends shaping the market. A hard push toward higher integrity and proper risk management practices, in a market that is unregulated but ought to perform on the same principles as a regulated one. A shift from avoidance credits to removal credits – a different instrument entirely, more complicated and far more capital intensive, closer to infrastructure development whether the work is planting a forest or building a direct air capture facility. And third, the convergence the panel came to discuss.
That third trend cuts both ways. Compliance demand creates true demand signals that are permanent, which is exciting. It is also alarming, because the compliance landscape is deeply fragmented.
Selling trust rather than credits
Eamon Jubbawy, Founder and CEO of Isometric, runs a carbon registry focused exclusively on removals – it issues no credits for avoidance activities, covering pathways from direct air capture and enhanced rock weathering through to reforestation.
His description of the business was unusually blunt: “we’re in the business of selling trust.” Buyers identify high quality projects and get excited about them, then need an independent third party to validate the claims being made.
Two components underpin that. Scientific rigour, with a bench of scientists writing the protocols that set crediting rules in line with best available science. And transparency, which he called the most critical component – defined as more than making information available. It means making it accessible and understandable so market participants can validate claims themselves.
That is a deliberate break from how the market has worked. The old approach put weight on a registry’s logo, conferring trust by virtue of being large and long-established. Jubbawy’s framing inverts it: build a trusted institution, but if you don’t want to trust us, inspect the data yourself. Don’t trust us – trust the data.
The analogy he drew was equities. Buying a stock comes with a standardized, deep layer of available data: reports, earnings calls, everything needed to build your own conviction. Standardizing carbon data the same way is what would let credits be bought, sold and traded as a financial asset without intermediaries constantly asking to be taken on faith.
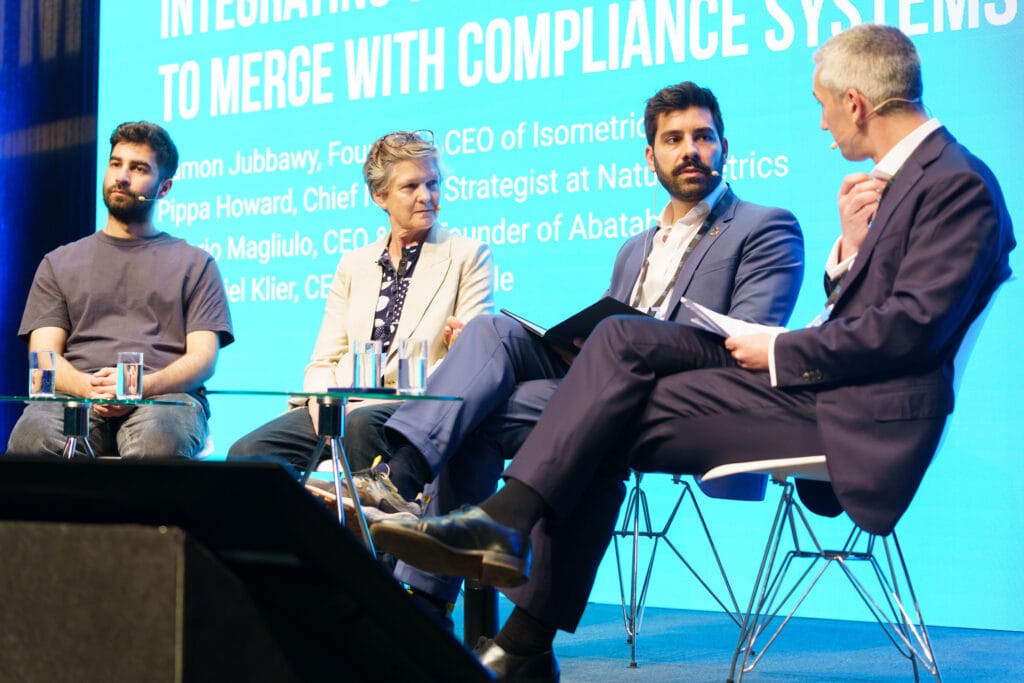
Discussion moderator Dr. Daniel Klier, CEO of South Pole and other panelists on stage
Voluntary supply, compliance demand
Valerio Magliulo, CEO and Co-Founder of Abatable, offered the cleanest formulation of the convergence: voluntary supply with compliance demand. Pricing mechanisms around the world are beginning to admit credits that have historically been voluntary.
Three consequences follow. The first is standardization. Transactions become far more standardized, because what the demand side cares about is eligibility against a compliance requirement – not the slew of impact metrics and storytelling that has dominated the voluntary market. For better or worse, that means commoditization.
The second, which he found more exciting, is an expansion of supply. Certainty of demand creates new markets for suppliers and investors deploying capital, and makes a path to growth visible.
The third is the uncomfortable one. The market becomes more fragmented, not less. The voluntary side already carries tens of standards and registries, many project types, and complications at local, regional and jurisdictional level. Overlay compliance requirements across multiple national schemes and Article 6, and it becomes a many-to-many relationship. A project developer no longer sells into a broad voluntary market – they have to ask whether they can sell into each specific national scheme.
Nature is not fungible
Klier framed the nature question precisely: a tonne of carbon is the same wherever it ends up, because it all reaches the same atmosphere. Nature is not fungible, so emerging compliance markets have to think local.
Pippa Howard, Chief Nature Strategist at NatureMetrics, argued that high integrity carbon has to include nature on the scorecard alongside social outcomes – there need to be biodiversity outcomes too.
The measurement problem is the obstacle. A molecule or an electron is comparatively easy to measure. Biodiversity means whole ecosystems, sometimes thousands or millions of species.
Her company is founded on environmental DNA – fragments of DNA collected from air, soil and water, amplified and matched to species. Combined with earth observation, bioacoustics and camera traps, that produces a three-dimensional understanding of an ecosystem and a set of state-of-nature metrics that can be tracked over time, which is precisely what monitoring, reporting and verification requires.
Cost has been the historic barrier, and her answer to it was the panel’s most concrete claim. Sending specialists into the field is expensive. The new technology removes that burden – a farmer or a local community can collect the data. Sampling a hectare is straightforward; sampling projects of tens or hundreds of thousands of hectares requires inference, which means understanding where to monitor and how often, supported by species distribution modelling and soil health data.
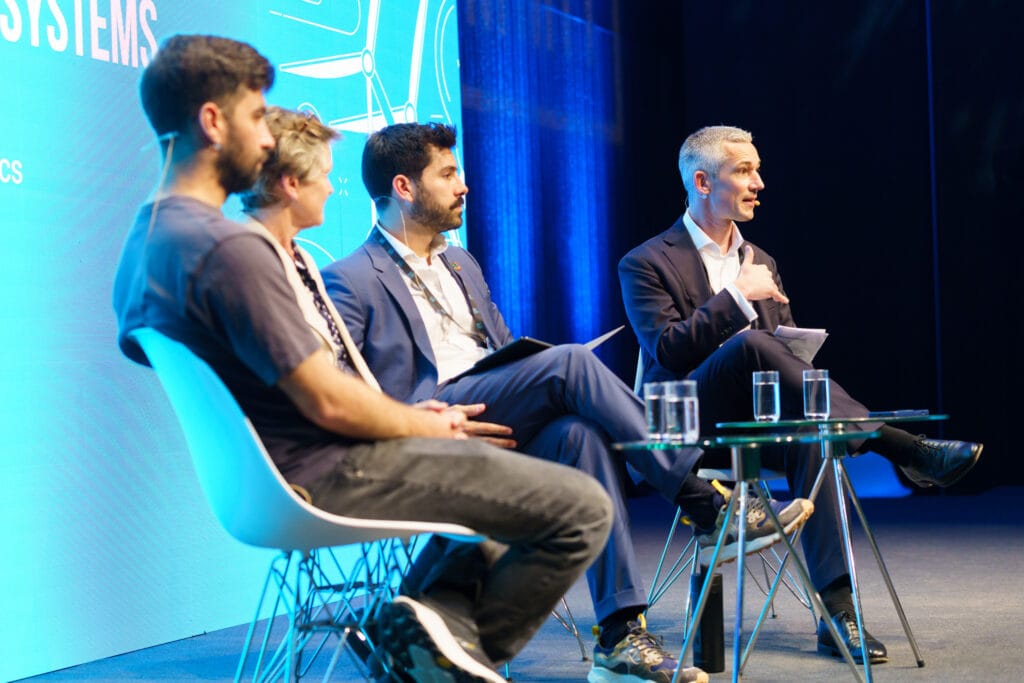
Panelists on stage
Why buyers are moving early
Klier raised the practical consequence: if convergence works, thousands of new actors enter a complicated market, and the average procurement team does not understand any of it.
Jubbawy described industries trying to get ahead of regulation they cannot yet see clearly. They don’t know exactly when it arrives or what it looks like, but they can read the trend toward quality and durability. Internal strategy teams price the risk of not complying, and knowing how supply-constrained the market is, long-term offtake contracts that secure supply and lock in price simply make business sense.
Layered on top of that is something more interesting than hedging. Particular industries are spotting a strategic role for themselves. Shipping, for instance, is realising that carbon removal is fundamentally a mass transfer problem – moving carbon atoms from one place to another – and shipping is good at that. Mining companies notice that spreading rocks on agricultural land is a promising removal pathway, and they have the rocks.
So becoming an early buyer positions a company both ahead of regulation and potentially inside the supply chain itself.
Who wins and who is exposed
Magliulo worked through the impact actor by actor.
For project developers, prices become dictated by eligibility rather than the true cost of developing a project – which makes some projects unviable, because the price ceiling in compliance markets sits below what it costs to plant a forest with a genuine biodiversity system in place. The sales cycle also becomes far more complex, since a developer in one country now has to understand how to sell into another country’s scheme. The compensation is certainty of demand, which developers have wanted for years.
For investors, the question is exposure. Those already in the market are asking whether their balance sheet is overweight in assets that will not be eligible for compliance markets. He argued that active asset developers – hold an advantage, because they can shape everything that happens after the seedling goes in the ground.
For host countries, the ones where projects sit, the requirement is administrative capacity to sustain international buyer demand. Harder still are the trade-offs against their own national targets: a forest-rich country can attract external capital to protect and restore forests, but those same forests count toward its own emission reductions. If someone offers more money for them, that becomes a difficult calculation.
For buyer countries opening emissions trading schemes to international credits, the balance is between admitting international supply and fostering local supply.
And for compliance buyers, this is starting from scratch. It is considerably more complex than trading allowances, requiring an understanding of eligibility. The upside is that it can be more cost effective, since allowance prices currently sit well above many carbon market projects. Existing voluntary buyers, meanwhile, face more competition for the same projects, as developers shift focus toward compliance schemes and shrink the available pool.
Takeaway
Asked what excites them on a three-year view, the panel gave three answers that describe the market’s direction. Jubbawy pointed to removals moving from laboratory to deployment, with real data coming back confirming the original theses – and a registry’s job being to verify that the claims are true. Howard pointed to measurement technology becoming scalable enough to bring new players in. With forest asset managers starting to value biodiversity alongside timber, and agriculture entering the equation. Klier wanted something simpler: to stop being asked whether carbon markets have a future, and to have a thriving financial ecosystem that has finally put a price on what is, for many corporates, a very large external liability.
Secure your pass
Energy Tech Summit brings together the startups, investors and corporates building the energy transition. Founder’s Pass is €699, fixed.